

The Ministry of Finance clarified taxes on the destruction of goods due to emergencies and UAV attacks
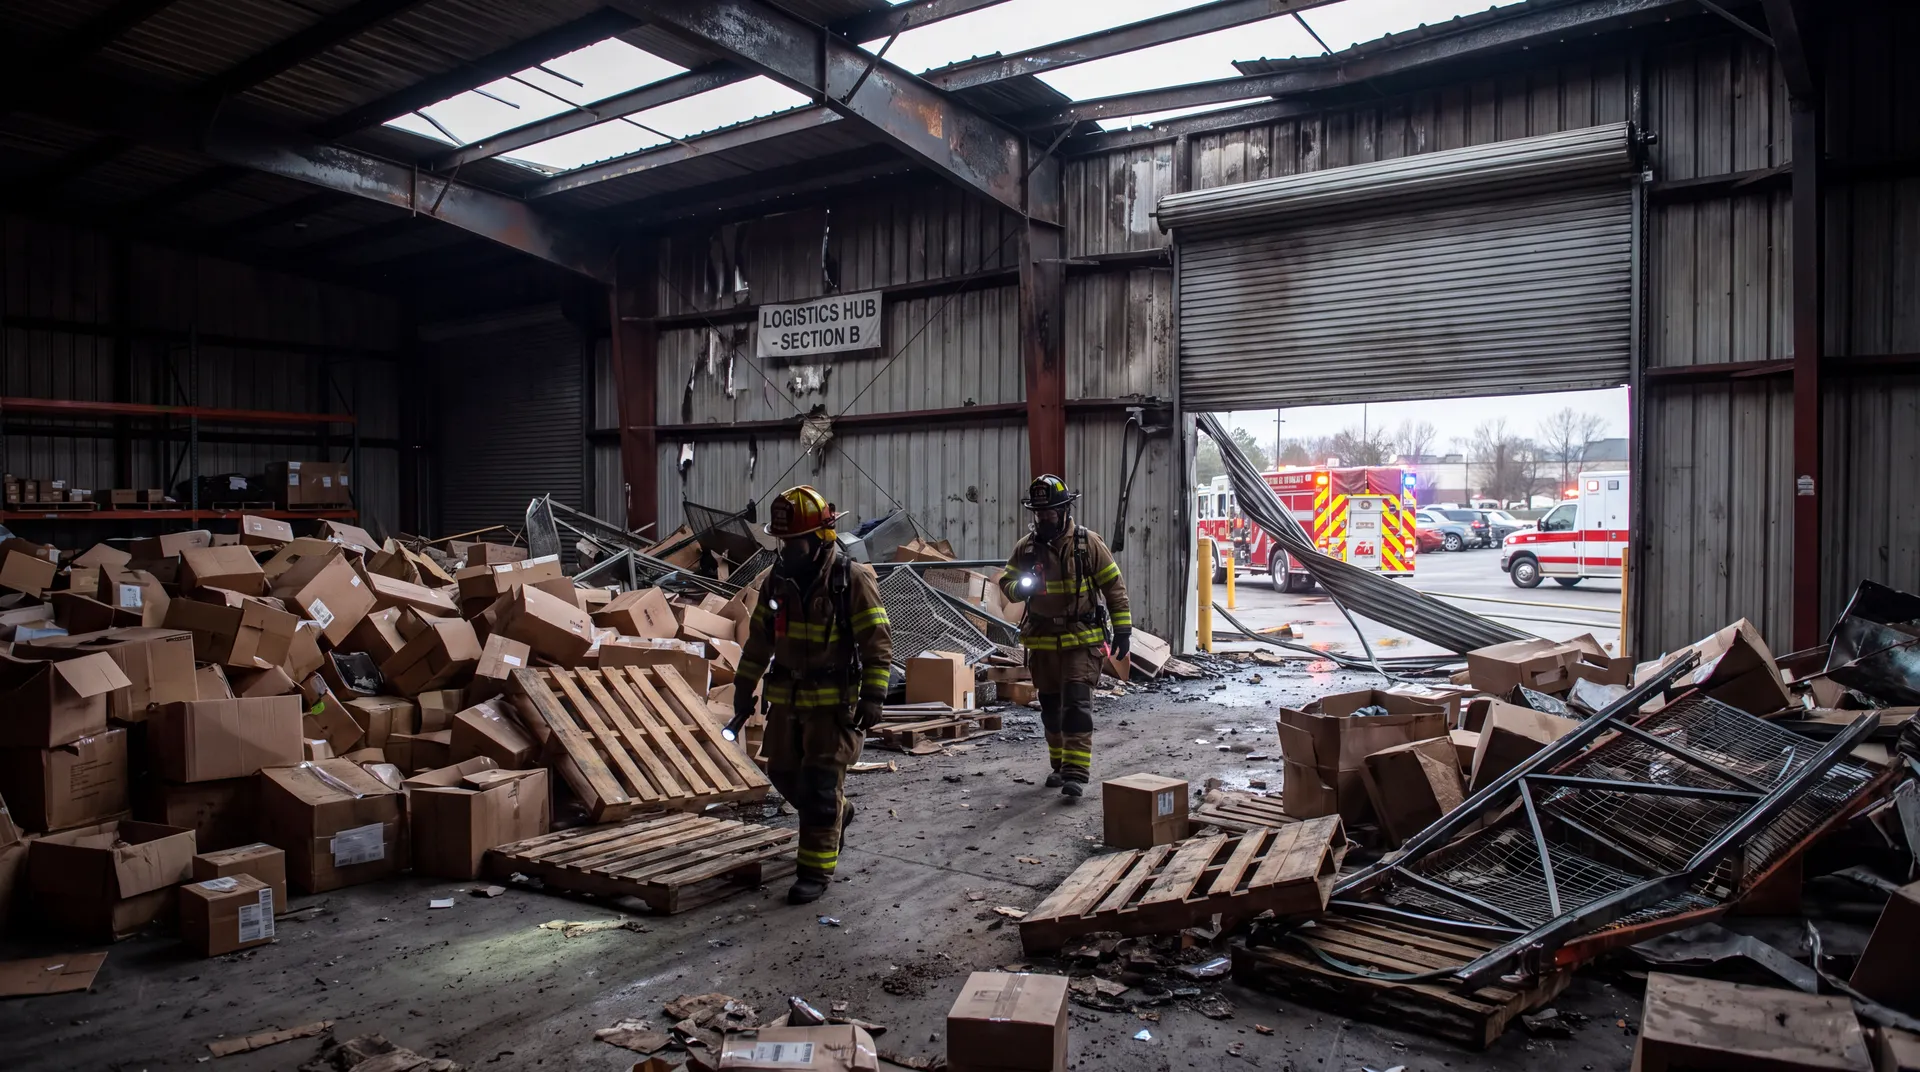
Letter No. 03-07-11/76470 from the Department of Tax Policy of the Ministry of Finance closes two specific issues faced by importers and distributors after the destruction of a warehouse or a batch of goods.
The VAT position is based on paragraph 1 of Article 146 of the Tax Code of the Russian Federation: the object of taxation is sales. Disposal of property as a result of events beyond the control of the taxpayer's will is not recognized as realization. The Ministry of Finance refers to paragraph 10 of Resolution No. 33 of the Plenum of the Supreme Arbitration Court of the Russian Federation dated May 30, 2014, which explicitly lists such cases as damage, combat, theft, and natural disaster. UAV attacks fall into the same category. The list of grounds for VAT recovery is fixed in paragraph 3 of Article 170 of the Tax Code of the Russian Federation and is closed — there is no destruction of property as a result of an emergency. The decision of the Supreme Arbitration Court of October 23, 2006 No. 10652/06 confirms this. The deduction lawfully applied upon purchase of the product remains in force.
For income tax, the mechanism is explicitly provided for in paragraph 2 of Article 265 of the Tax Code of the Russian Federation: losses from natural disasters, fires, accidents and other emergencies relate to non-operating expenses. The Ministry of Finance clarifies that losses are recognized in the accounting or tax period in which the destruction of valuables occurred. The organization has the right to write off the cost of lost goods and the costs of eliminating the consequences of an emergency — clearing debris, removing damaged property, and conducting an expert examination.
Documentary confirmation is a prerequisite. The Ministry of Finance points out the need for acts of authorized bodies: the Ministry of Emergency Situations of Russia, the Investigative Committee, and the police. It is these documents that record the fact and reason for the destruction of property and allow you to avoid disputes during the tax audit. The initiator of the appeal to the Ministry of Finance proposed to legislate the unconditional right to a 100% write-off of the cost of goods on the basis of such acts. The Agency did not introduce new regulations, pointing out that the current legislation is already sufficient to account for such losses.
For participants in foreign economic activity, the explanation is especially relevant: imported goods are often stored at large logistics facilities that become targets of attacks. There is no need to restore VAT on shipments processed at customs and destroyed before sale. Losses from such losses reduce the tax base for profits during the destruction period, provided that the act of the Ministry of Emergency Situations or another body is issued in a timely manner and contains the reason for the incident.
Related news:
- The Ministry of Finance has prescribed how to calculate VAT if the law has changed after the contract
- The Ministry of Finance proposed VAT on foreign goods with MP: 7%→14%→22%
- 22% VAT and 18.03% rate: what has changed for importers in 2026
- The Ministry of Industry and Trade wants a 22% VAT on foreign parcels from 2027 — the Ministry of Finance is against a sharp jump
- Importers were given a three-month VAT delay