


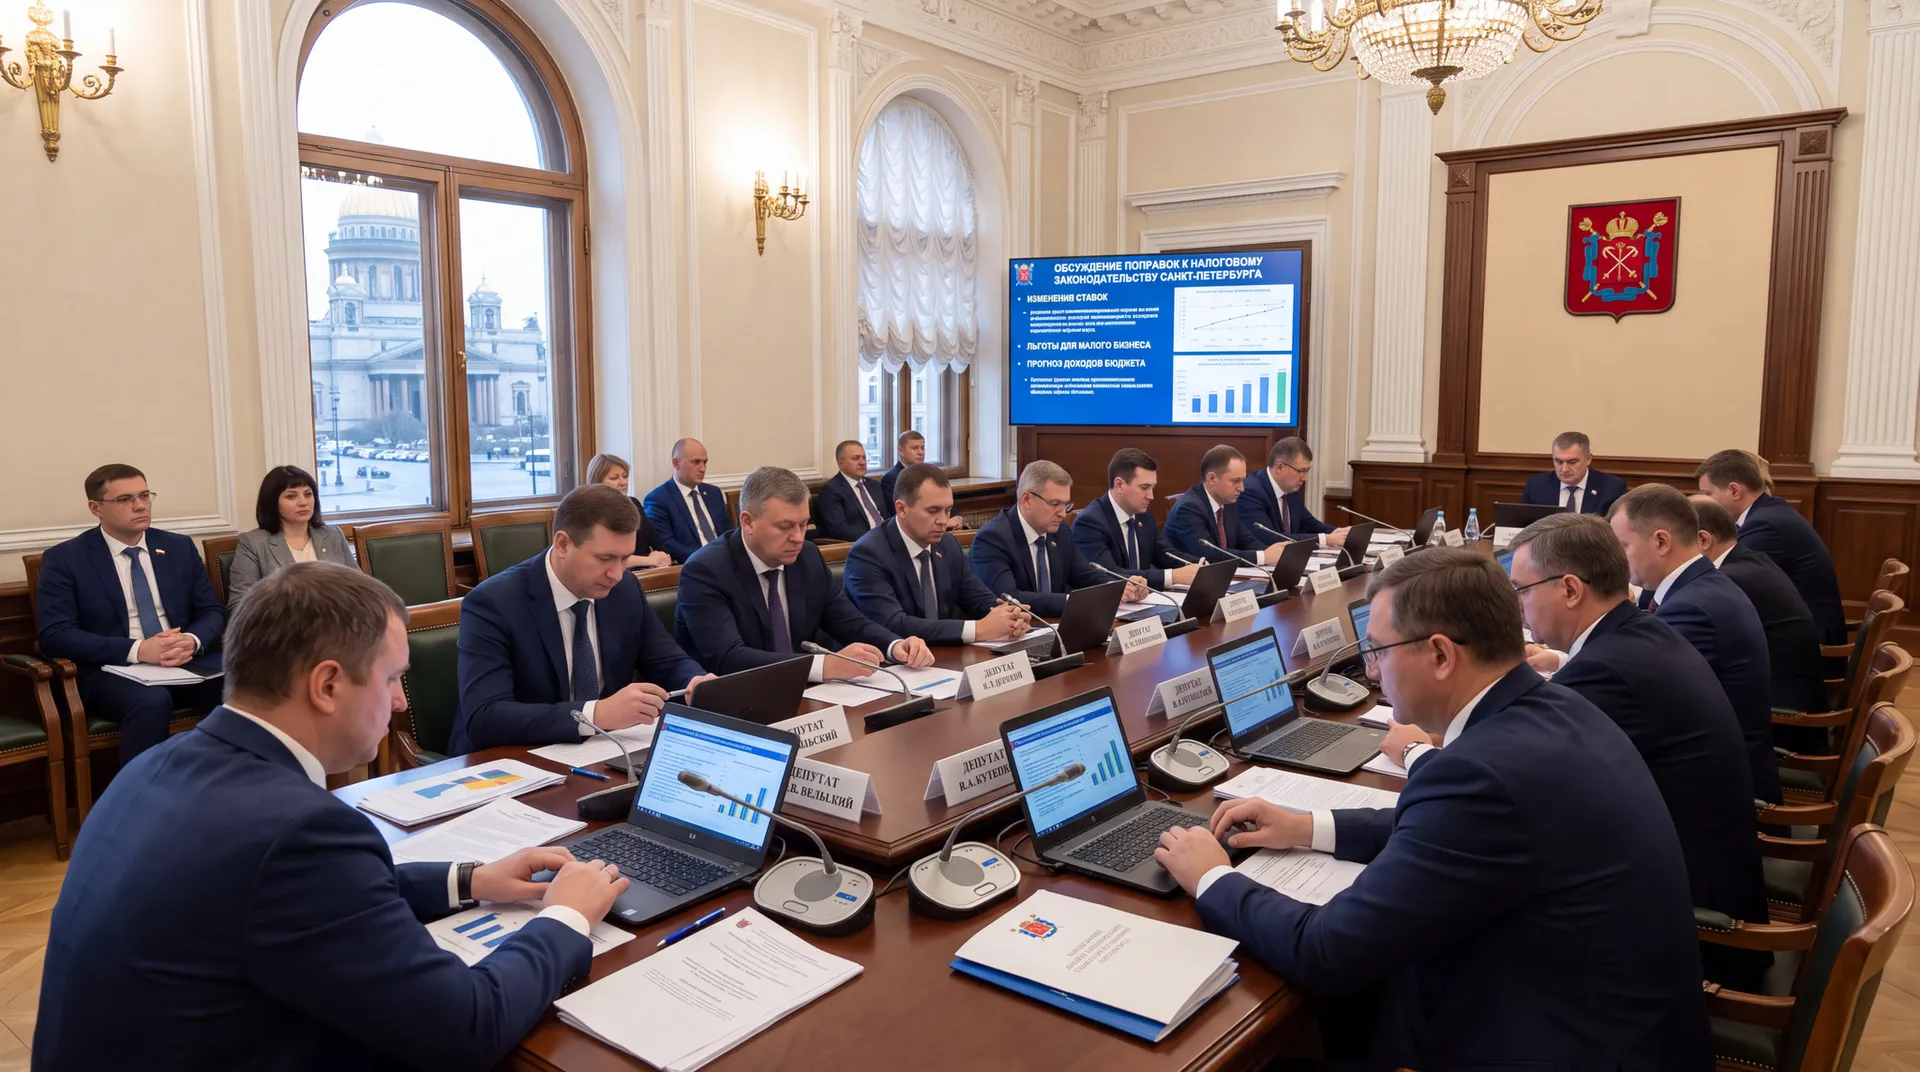
On November 9, the issue was considered at a joint meeting of the budget and finance committee and the commission on industry, economy and entrepreneurship. The proposal is to remove the preferential 7% rate for the "income minus expenses" object, leaving a single base rate of 15%.
280 thousand companies and individual entrepreneurs in St Petersburg apply the simplified tax system. Of these, just over 100 thousand use the reduced 7% rate. For other payers on "income minus expenses", 15% already applies.
In 2026, the right to the preferential rate depends on three requirements:
- the main type of activity must be on the federal list of eligible OKVED codes;
- the company must have no tax arrears;
- the average salary of employees must not fall below the St Petersburg minimum.
If the amendments are adopted, this combination of conditions will lose its meaning: for most, there will simply be no benefit left for the "income minus expenses" object.
An exception is planned for accredited IT companies and small technology companies. For them, it is proposed to keep a rate of 1% of income and 5% for the "income minus expenses" object.
For businesses currently paying 7%, the switch to 15% means a more than twofold increase in the tax burden. This is especially noticeable for companies with a high share of confirmed expenses: they chose "income minus expenses" as the more advantageous object.
There is time to recalculate the financial model: the law, if adopted, will take effect on January 1, 2027. Before then, it is worth assessing whether it is more profitable to stay on "income minus expenses" at the new rate, switch to the "income" object — at a rate of 1%, if the type of activity allows — or consider changing the tax regime altogether.
For St Petersburg importers and exporters on the simplified system, the change directly affects the cost of operations: tax on the margin from foreign trade contracts will rise, requiring a review of price terms with counterparties or the cost structure.
No final decision has yet been made. The status of the bill can be tracked on the official website of the St Petersburg Legislative Assembly.
Related news:
- The Ministry of Economic Development approved simplified system limits for 2027: new 5% and 7% VAT thresholds — federal simplified system limits and VAT thresholds for 2027
- Fixed asset limit under the simplified system to rise to 230.6 million roubles in 2027 — fixed asset limit for the simplified system in 2027
- Deadline for notice of switching to the simplified tax system from 2027 moved to January 11 — by what date to file the notice of switching to the simplified system
- Taxes for individual entrepreneurs in 2027: patent, VAT under the simplified system and new contributions — tax changes for entrepreneurs from 2027
- Simplified system and VAT in 2026: step-by-step guide for those becoming VAT payers — what to do if a simplified system taxpayer becomes liable for VAT