

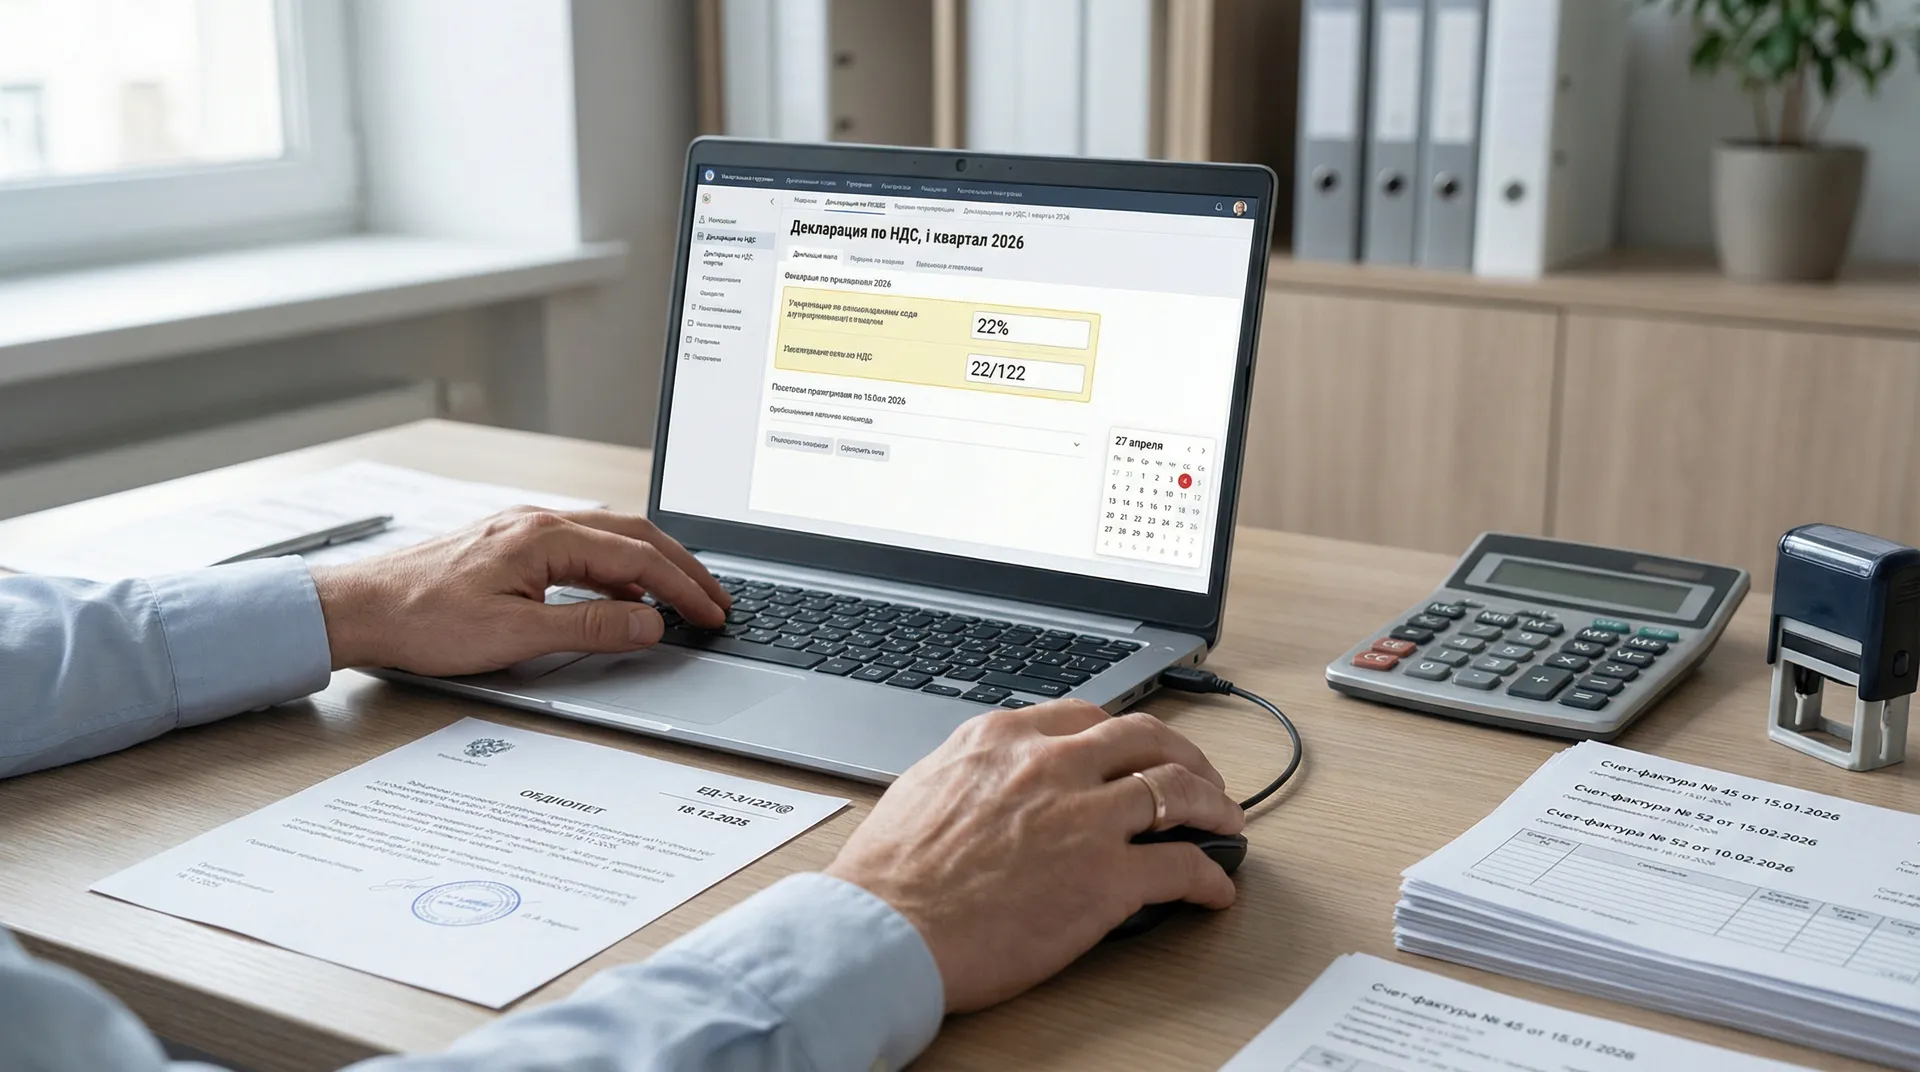
The Federal Tax Service reminded businesses of an important fork at the junction of rates and reporting: "The VAT declaration for the first quarter should be submitted in an updated form." We are not talking about cosmetic changes to the form — the form has been rebuilt to fit the new reality, where the base VAT from January 1, 2026 is 22%. The declaration for the first quarter must be submitted by April 27, while the order of the Federal Tax Service dated 12/18/2025 No. ED-7-3/1227@ comes into force on March 29, 2026.
The main reason for the changes is the transition to 22%. In section 3, there are separate lines for accruals at rates of 22, 22/122 and 18.03%. This is critical for companies with advances and a long execution cycle: some operations “flow” across the border on January 1, 2026, which means that it is important for accounting to correctly separate the tax base and the time of determining the rate. An incorrect line in the declaration is a common reason for clarification requirements and discrepancies with purchase/sales books.
The second most important edit is sections 8 and 9. Details have been added there to indicate the numbers and dates of shipping and advance invoices. This looks like a step towards a more “machine-readable” reconciliation: the Federal Tax Service strengthens the connectivity between shipment and prepayment at the primary and reporting levels. This is especially sensitive for foreign economic activity companies: advances on import contracts, partial shipments, adjustments, and document chains are often time-consuming, which means that new fields increase the requirements for accounting discipline and data quality.
The third direction is to expand the list of VAT—free transactions with new codes. The updates include, in particular, transactions on the transfer of goods (works, services) to military units for use in their own territories, the transfer of seized real estate for state (municipal) needs, as well as interest payments in precious metals in bullion by banks under a deposit agreement. In practice, this means that it is important for the accountant not only to choose the correct code, but also to prepare a set of supporting documents so that the release does not “fall apart” during the desk check.
What to do right now to get through the first quarter without surprises:
- update the accounting system/upload formats for a new declaration;
- check invoice templates and bundles “advance → shipment” (numbers/dates);
- take inventory of contracts and advances that fall on the transfer rate;
- to verify the application of the new non-taxable transaction codes and the “evidence base”.
The new form is not bureaucracy for the sake of bureaucracy, but a 22% control setting and more accurate invoice traceability.