

The Federal Customs Service and the Ministry of Finance are looking for a unified approach to customs value for ruble payments
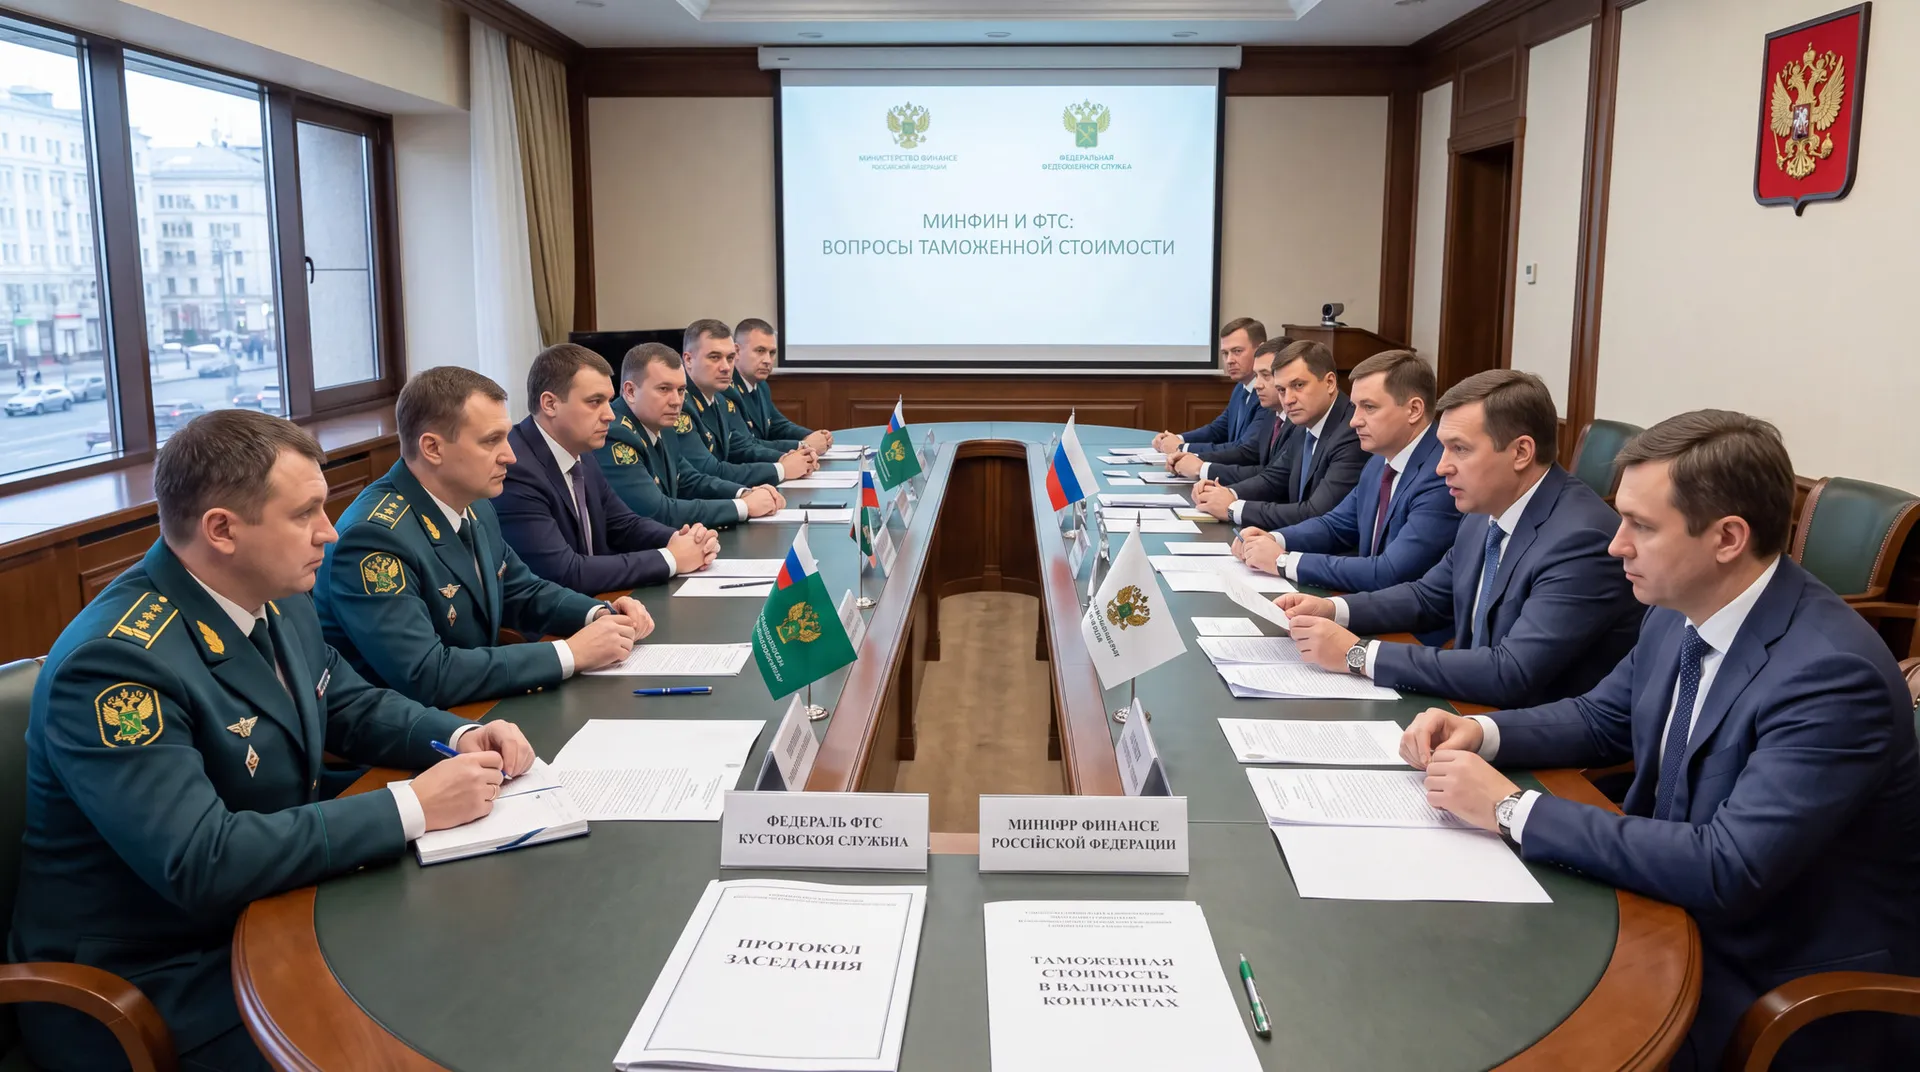
The Permanent Commission of the Expert Advisory Council on the Implementation of Customs Policy at the Federal Customs Service of Russia held a meeting at which it analyzed the procedure for calculating customs value for ruble payments under foreign exchange contracts. A representative of the Russian Ministry of Finance participated in the discussion.
The controversial situation looks like this: in the contract and invoice, the price of the goods is indicated in dollars or euros, the Russian buyer transfers rubles to the seller, and the declaration for the goods is submitted later. Article 38 of the EAEU Labor Code establishes a general rule — if a recalculation of foreign currency is required, the exchange rate on the day of registration of the declaration is used. The question is whether to apply this rate to the amount that the buyer has already actually paid in rubles before submitting the DT.
The Ministry of Finance responded in a letter dated February 12, 2025 No. 27-01-21/12637. The Agency concluded that for the part of the expenses paid in rubles before the registration of the declaration, a recalculation at the exchange rate on the date of the tax return is not required — the amount actually incurred is included in the customs value. If a part of the obligation has not yet been repaid on the date of registration, the exchange rate on the day of registration of the declaration is applied to it.
Judicial practice shows that the issue is solved differently. In one of the cases, the arbitration court considered a situation where the price of goods was set in dollars, and payments were made in rubles at the rates agreed by the parties. The dispute concerned exactly what should be considered the customs value: the amount of actual ruble transfers or the result of recalculation at the official exchange rate on the date of registration of the DT. The amount of the declared customs value and the amount of customs payments directly depend on the chosen approach.
A separate discussion block concerned settlements through payment agents. Two independent questions arise here: what amount is considered actually paid for the goods and whether it is necessary to include the intermediary's remuneration in the customs value. The position of the FCS, developed at a meeting of the standing committee on June 28, 2024, distinguishes between the two cases. If the payment agent acts in the interests of the seller, his remuneration may be included in the customs value as an agency fee. If the agent acts in the interests of the buyer, such remuneration is not included in the Customs value under appropriate circumstances. In practice, it remains essential to document in whose interests the agent is acting and for which service the commission is charged.
This position has already been taken into account in court disputes, but the documentary basis for each transaction still determines the outcome.
The current discussion covers several related elements of an import transaction at once: the currency of the invoice, the time of payment, the method of transferring money, and the structure of additional costs. The Commission collects practical situations, compares the positions of the Federal Customs Service, the Ministry of Finance and Business and forms a unified approach. The next step may be to formalize the agreed Russian position and present it on the site of the Eurasian Economic Commission. Before making decisions at the EAEU level, importers will have to rely on the current norms of the EAEU Labor Code, clarifications from the Ministry of Finance and the Federal Customs Service, as well as carefully document the terms of each specific transaction.